Budgeting for realized gains
Tax practitioners can help clients achieve a more predictable and profitable tax cost.
For most of us, budgeting scarce resources is a necessity in our daily lives—and paying taxes is no exception. The importance of budgeting for realized gains, both in the planning and execution phases of investing, cannot be overstated. Regardless of the vintage (inception date of the investment) or subsequent market path, disciplined planning for realizing gains lessens the potential for unanticipated taxes or ugly year-end surprises. This is especially the case for retirees whose income tends to be fixed and thus for whom unplanned tax costs are more challenging.
Establishing and adhering to a well-designed gain budget can provide both tax and investment advisory professionals with a blueprint of acceptable net realized gains to be taken over the course of the tax year. An in-depth understanding of budgeting for gain realization provides the investment adviser/portfolio manager with guidelines on acceptable transactions and may go a long way toward maintaining investment discipline. In the Feb. 16, 2017, Tax Insider we published an article titled “Reexamining Tax-Loss Harvesting: Better Results Through Enhanced Understanding.” In it we focused on the importance of tax professionals in supporting tax-loss harvesting and thus improving after-tax outcomes for clients.
The basics
Let’s review the technique of gain budgeting. When purchased securities rise above their initial purchase price (or basis), they generate a gain for tax purposes when sold. Short-term realized gains are gains on securities held for less than one year, while long-term gains are gains on securities held for more than a year. Realized gains may be offset by losses realized elsewhere in the portfolio.
The highest tax rate that applies to long-term gains (20%) is about half the highest rate of short-term gains (39.6%). Short-term losses are applied against both short-term gains and long-term gains, and portfolios with short-term losses and no long-term losses must use these more valuable short-term losses to offset long-term gains. The technique of gain/loss budgeting involves planning the size and timing of gains that can be realized in a given year.
Through the use of separately managed accounts in taxable portfolios (unlike mutual funds or exchange traded funds (ETFs) where each sale is representative of all underlying securities), advisers/portfolio managers can harvest client gains and losses on a security-by-security basis.
Building a loss reservoir through tax-loss harvesting can go a long way toward offsetting necessary transactions and the gains they often create. Most advisers are reluctant to take responsibility for budgeting for realized gains because it makes their job more complex. Further, investment management professionals usually focus only on pretax returns when measuring their success compared to their peers. Nonetheless, after-tax returns are what really matter to high-net-worth investors.
Tips on improving each client’s after-tax results
Each client’s gain budget will have to be adjusted based upon market conditions—especially during periods of market volatility. During a strong market downturn, loss harvesting may grow the realized loss reservoir rapidly. Alternatively, after an extended rally, the realized loss reservoir may be exhausted, requiring an increase in the gain budget later in the market cycle.
Thoughtful asset location management, essentially placing taxable assets in more tax friendly locations (such as deferral accounts), may support a better outcome. This type of planning (between taxable and deferral accounts) can reduce realized gains, though new Labor Department rules requiring securities in deferral accounts be diversified may limit its use.
Take full advantage of challenging markets by building a reservoir of realized losses to offset eventual gains by using tax loss harvesting. Advisers and portfolio managers are often guilty of “doubling down” on poorly performing stocks, which can damage investment returns. Further, when loss harvesting, market timing should be avoided by purchasing representative stocks (to replace those sold) throughout the wash sale window.
Avoid unnecessary turnover through maintaining a long-term, multiyear approach to investing and using highest-in, first-out (HIFO) accounting. HIFO uses inventory accounting to minimize the tax bite.
All parties should agree to budgeting for gain buy-in from all parties through ongoing communication. Once established and agreed to, the gain budget should be adhered to.
An example
Here is an example of the power of disciplined gain budgeting:
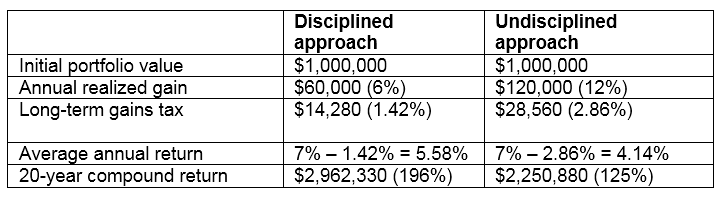
Note: We assume a 7% annualized return on stocks with no withdrawal over a 20-year time frame. Gains are assumed to be entirely long-term in character (taxed at 20% long-term capital gain tax + 3.8% net investment income tax). As we do not tax-loss harvest and thus have no losses to offset gains in this example (as would likely be the case after a sustained rally) 6% is a reasonable gain budget.
As the above example demonstrates, high-net-worth investors potentially can achieve greater investment returns when budgeting for realized gain is used.
Today’s fully priced stock market means investors are at greater risk of a significant principal drawdown or even portfolio impairment when the next bear market sets in. Impairment in the market, which can result in losing as much as 20% of portfolio assets, can be a nightmare for retirees and must be avoided wherever possible. Thoughtful management and allocation of a client’s assets is now more important than ever. Unnecessary gain realization should be avoided, yet taxes alone should not be allowed to drive important investment decisions. A disciplined approach to realizing gains in both the planning and executions phases of portfolio management should result in a significantly improved outcome for clients.
Budgeting realized gains supports an improved after-tax outcome. And this service, especially for retirees, is most often in the tax professional’s area of expertise because investment advisers/portfolio managers may be unfamiliar with or reluctant to engage in this activity.
Steve Riley (steve@clearviewws.com), and Rick Furmanski (rick@clearviewws.com), are portfolio managers at Clearview Wealth Solutions in Barrington, Ill.